

Multi-Use Battery Storage · for Industry from 1 MW
Multi-use battery storage: More cycles ≠ more revenue. It’s the control logic that decides.
Three revenue channels in parallel on the same hardware: FTM marketing on balancing energy and spot markets, BTM optimization against peak loads and grid fees, co-location and self-consumption under MiSpeL (since October 2026). The hardware is multi-use-capable. The control is multi-use-optimized. The difference lies in the EMS, not in the cell.
240–320 k€
FTM gross / MW / year
FCR + aFRR + mFRR + Arbitrage
2–4 years
Typical payback
BESS purchase · CUBE CONCEPTS benchmark
~250 €/kWh
CAPEX up to 2 MWh
From 5 MWh: 175–200 €/kWh
January 1st, 2027
Section 118: investment cut-off date
according to the AgNes draft · commissioning by 4.8.2029
Home " Battery storage " Multi-use
Table of Contents
ToggleReal modeling
320,100 € cash flow in the “AgNes price-led” scenario – 1.5 years payback. Status quo: 97,200 €.
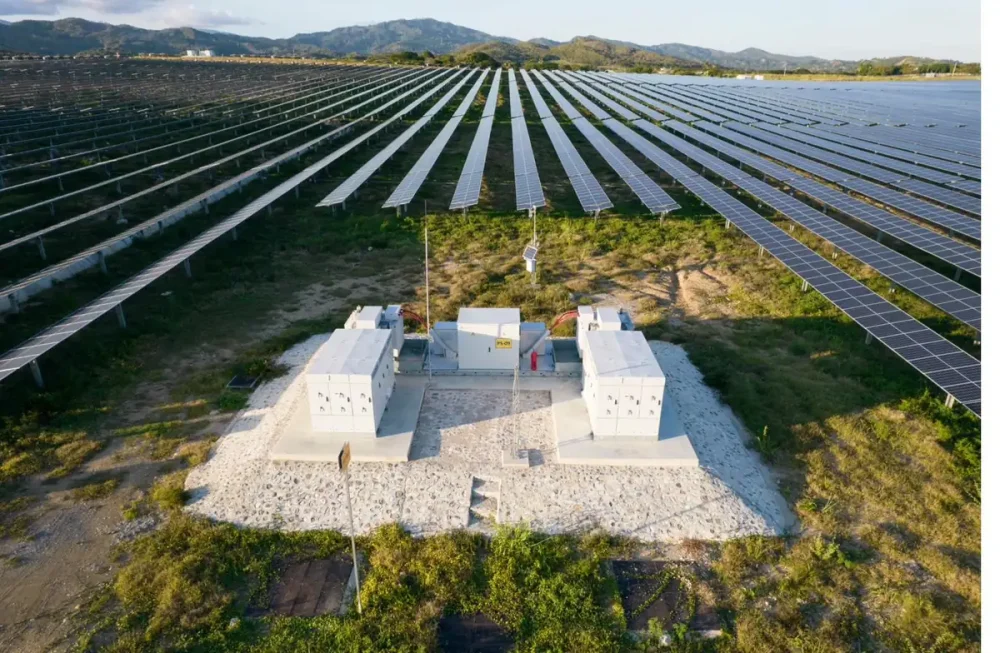
CUBE CONCEPTS modeling at a real industrial site in Saxony. 1 MW / 2 MWh BESS, 1,895 kWp existing PV, 6,795 MWh annual consumption, peak load 1,284 kW, grid fee bill ~310k €/year. Modeling in three regulatory configurations based on real half-hourly load data.
Status quo (StromNEV 2026)
€97200
Total Annual Cash Flow
of which CUBE 75 %
€72900
of which customer 25 %
€24300
Payback
5.3 yrs
Project IRR
17.2%
NPV
€328k
AgNes scenario, grid-driven
€226500
Total Annual Cash Flow
of which CUBE 75 %
€169875
of which customer 25 %
€56625
Payback
2.2 yrs
Project IRR
58.6%
NPV
€1.66M
The lever
AgNes scenario, price-driven
€320100
Total Annual Cash Flow
of which CUBE 75 %
€240075
of which customer 25 %
€80025
Payback
1.5 yrs
Project IRR
94.0%
NPV
€2.70 million
The regulatory configuration determines the leverage; Multi-Use makes it usable. Factor 3.3 between the lower and upper limit – with identical hardware, identical control, and the same location.
What do the three configurations mean? Status quo (StromNEV 2026): current regulation with §19 atypical grid usage, valid until 31.12.2028. The two AgNes scenarios represent models B (grid-driven: storage follows grid utilization signals) and A (price-driven: storage follows spot market prices) from the BNetzA discussion paper of 24.09.2025. The draft determination of 06.08.2026 instead provides for a capacity price on the ordered capacity, no successor to atypical grid usage, and discounts only for system-supportive flexibility. The scenarios therefore show a range; CUBE CONCEPTS will recalculate them with the final determination (planned for the end of 2026).
Note on the PV portfolio: The modeled site has 1,895 kWp of PV capacity – this impacts BTM cash flows (self-consumption optimization). Sites without PV continue to achieve FTM cash flows in full. Multi-Use is completely PV-independent – the PV capacity amplifies the leverage, but is not a prerequisite.
Source: CUBE-CONCEPTS load flow modeling April 2026 · BNetzA discussion paper 24.09.2025 (Model A/B) · BNetzA guidance points for storage network tariffs 16.01.2026 and feed-in tariffs 17.02.2026 (AgNes, GBK-25-01-1#3) · BNetzA, AgNes draft regulation from 06.08.2026 · KPMG AG, Investment Case: Stationary battery storage, Feb. 2026 (assumptions)
What you will find on this page
Four levels of depth on multi-use
The multi-use question has four meaningful entry points – depending on whether you want to understand the control mechanism, follow the economics, know the regulatory levers, or compare the business models.
Control logic
How the EMS control system automatically resolves three daily conflicts – FCR vs. peak shaving, arbitrage vs. §19, cycle threshold value.
Skip to section →
Skip to section →
Regulatory Levers 2026/2027
Section 118, paragraph 6 of the EnWG, Section 19 of StromNEV/AgNes, MiSpeL, EEG Amendment 2027, Solar Spitzengesetz, Section 11c of the EnWG (storage = overriding public interest), Outdoor privilege §35 BauGB.
Skip to section →
Business Models: Buy vs. Contracting
0 € CapEx with Contracting and a 25 % profit share for the customer – or full investment with 100 % of revenues with a purchase.
Skip to section →
Control logic
How does the controller automatically resolve three daily conflicts?
Multi-Use sounds simple. In practice, three conflicts arise daily that must be resolved automatically, without production intervention.
01
FCR Readiness vs. Peak Shaving Capacity
FCR requires a sustained ~50 % SoC – this ties up capacity that is not available for peak shaving. The CUBE EfficiencyUnit prioritizes hourly based on peak load time windows, load forecast, and market price. FCR causes only ~0.3 full cycles/day – low degradation with significant revenue contribution.
02
Arbitrage window vs. § 19 para. 2 sentence 1 peak load time window compliance
Cheap charging periods conflict with the grid operator’s peak load time windows. §19 atypical grid usage requires that the maximum load in the peak load time windows is significantly below the annual maximum load; charging from the grid during these windows jeopardizes this condition. The CUBE EfficiencyUnit knows all peak load time windows and automatically blocks charging. Proof can be exported directly. Deadline: June 30 of the following year.
03
Cycle Threshold: When is a cycle not worth it?
If the price range is smaller than the proportionate cycle costs (degradation + OPEX), the cycle reduces the overall margin. The CUBE EfficiencyUnit calculates the threshold dynamically and executes only profitable cycles. That is the difference between multi-use capable and multi-use optimized.
Multi-use capable vs. Multi-use optimized
Multi-Use Capable
Hardware Claim
The system is technically capable of multiple operating modes. Manual switching. No automatic conflict resolution. Manual update of peak load time windows. FCR and peak shaving are not simultaneously coordinated. §19 compliance depends on operator decisions.
Multi-Use optimized
CUBE EfficiencyUnit
Automatic real-time prioritization of all revenue channels. Peak load time windows updated daily. Cycle threshold calculated dynamically. FCR SoC hold point + peak shaving capacity simultaneously. §19 compliance automatically documented. From 2029: control to the ordered capacity under AgNes on the same platform.
Illustrative Daily Schedule of a Multi-Use Battery Storage System
22:00 – 06:00
Cheap charging
Low market prices. Arbitrage charging. FCR standby at 50 % SoC in parallel.
06:00 – 08:00
Morning ramp
Increasing grid load. Check §19 peak load time windows. Partial discharge for peak shaving readiness.
08:00 – 12:00
Peak Shaving Active
Peak load time window active. Discharge during peak loads. §19 compliance automatically secured.
12:00 – 16:00
PV / Recharging
With PV: self-consumption optimization. Without PV: favorable price windows for recharging.
16:00 – 20:00
Evening peak
Peak shaving + arbitrage discharge. Peak load time window: charging blocked – §19 compliance active.
20:00 – 22:00
FCR / Standby
Balancing energy standby. 50 % SoC. §19 annual documentation in progress.
Illustrative daily schedule – actual control is site-specific and reacts in real time to market and grid signals. The CUBE EfficiencyUnit makes all prioritization decisions fully automatically.
Next step
Control Logic Check: How much is your facility leaving on the table today?
Three phases & trajectory
From day-one FTM operation to full multi-use
Multi-Use is not a Big Bang, but a regulated escalation of monetization. Three phases on the same asset – without hardware changes.
01
FTM & BTM combined
FTM: FCR + aFRR + mFRR as a supplementary channel + spot market arbitrage via top-tier aggregator. BTM: Peak shaving against demand charges & Section 19 (2) sentence 1 StromNEV (until Dec 31, 2028). Fully automatic, no operational intervention.
→ FTM revenue 240–320 k€/MW/year + BTM leverage
02
Phase II · MiSpeL since Oct. 2026
PV Co-Location added
With MiSpeL: Hybrid storage (PV + grid) without loss of EEG subsidies under § 19, paragraph 3b of the EEG. PV sites can now combine arbitrage and EEG feed-in for the first time, without the previous either-or situation.
→ Self-consumption + FTM without loss
03
New grid fee system
The StromNEV expires on December 31, 2028; AgNes replaces it. According to the draft of August 6, 2026, industrial customers pay a capacity price on the ordered capacity; consumption above it costs 2 to 3.5 times the energy charge. Co-location storage systems pay a joint fee with the facility; quantities drawn from the grid and fed back are exempt from the energy charge if metered separately.
→ The storage system keeps consumption below the ordered capacity
Regulatory Trajectory 2025–2029
The regulatory changes from 2025 to 2029 do not act in isolation but as a shift from feed-in to self-consumption. Most levers strengthen multi-use; the end of atypical grid usage in 2028 shifts the BTM lever from the peak load time windows to the ordered capacity.
| Date | Hebel | Impact on Multi-Use |
|---|---|---|
| since 25.02.2025 | Solar Peak Act (Solarspitzengesetz) | New PV installations do not receive EEG compensation at negative prices; in 2025 there were 573 hours with negative wholesale prices. PV sites secure their profitability with storage. |
| 18.07.2025 | Immediate investment program | BGBl. 2025 I No. 161: declining-balance depreciation of up to 30 % (§7 para. 2 EStG) for all companies, for acquisitions from 1.7.2025 to 31.12.2027; can be combined with the existing special depreciation under §7g para. 5 EStG (up to 40 %) for prior-year profits up to €200,000. |
| 23.12.2025 | EnWG and BauGB amendments | §11c EnWG: Energy storage systems are in the overriding public interest. §35 para. 1 nos. 11 and 12 BauGB (German Building Code) privilege battery storage systems in the outer zone: in spatial and functional connection with an existing renewable energy plant, or from 4 MW at most 200 m from a substation or a power plant of 50 MW or more. Since December 2025, the §118 exemption also applies to partial feed-back into the grid. |
| Q1 2026 | AgNes key points | BNetzA (GBK-25-01-1#3) has published guidance on storage grid fees (16.01.2026) and feed-in grid fees (17.02.2026). |
| 16.04.2026 | Industrial electricity price | EU approval (SA.120495). Eligible: sectors in KUEBLL sub-list 1, 91 sectors and subsectors according to the BMWE. Reinvest at least 50 % of the granted amount within 48 months, energy storage explicitly mentioned. 10 % bonus if 80 % of the commitment flows into demand-side flexibility. |
| 29.07.2026 | EEG Amendment 2027 | Cabinet decision, BT-Drs. 21/7867: Direct marketing obligation for new installations (gradual), permanent feed-in limit of 50 % for building PV below 100 kW, two-sided contracts for difference from 100 kW. Not yet adopted; planned from 1.1.2027. Self-consumption with storage is gaining in value. |
| 06.08.2026 | AgNes draft determination | Capacity price on the ordered capacity; no successor to atypical grid usage. New grid-connected storage systems will pay a capacity fee from 2029 (BNetzA estimate 4–7 €/kW per year), no energy charge. §118 exemption for new projects only if the investment decision is made before the determination is announced. |
| 01.10.2026 | MiSpeL determination | Hybrid storage (EEG and grid electricity) without loss of EEG support under § 19, paragraph 3b of the EEG; until 30.09.2027 with the consent of the grid operator and metering point operator. |
| 31.12.2026 | §118 cut-off date (draft) | Last day for the final investment decision to secure the 20-year exemption under §118(6) of the EnWG; announcement of the AgNes determination planned for January 1, 2027. |
| 01.01.2029 | AgNes launch | StromNEV is no longer in effect; the new grid fee system applies. Transitional discounts for existing users until the end of 2031 (draft). |
| 04.08.2029 | §118 commissioning deadline | Last commissioning date for the 20-year exemption from grid fees on electricity consumption, insofar as electricity is fed back (Section 118(6) of the EnWG). |
Source: BNetzA, AgNes-Draft Regulation from 06.08.2026 · BNetzA guidelines from 16.01.2026 and 17.02.2026 · BNetzA/SMARD, 20.08.2026 · BGBl. 2025 I No. 161 · §11c EnWG · §35 BauGB · BT-Drs. 21/7867 · BMWE, Press release 16.04.2026 · BNetzA, MiSpeL-Draft
Investment Case
How does a gross revenue of 240–320 k€ become a FTM net revenue of 185–265 k€?
Multi-use revenues do not equal gross revenue. Marketing costs and fixed OPEX must be deducted before the net result appears in the investment case.
FTM Gross Proceeds per MW/Year (FCR + aFRR + mFRR + Arbitrage)
240–320 k€
− OPEX including marketing (aggregator commission, maintenance, insurance, substation, monitoring)
-55 k€
FTM net per MW/year
185–265 k€
FTM gross revenue 240–320 k€/MW/year and OPEX of around 55 k€/MW/year including marketing: CUBE CONCEPTS guideline values for multi-use FTM (FCR, aFRR, mFRR, arbitrage). For comparison: according to the ISEA Battery Revenue Index, the cross-market revenue potential of a 2-hour storage system was around €259,000/MW in 2025 (2024: around €309,000/MW). Actual revenue depends heavily on location, marketer and market phase; site-specific modelling is required. Source: ISEA Battery Revenue Index, via pv magazine 23.01.2026.
KPMG comparison calculation – Stationary battery storage
Assumptions of the simplified comparison calculation: 10 MW BESS, 4-hour profile (40 MWh), 2 full cycles per day, 140 €/MWh sale, 30 €/MWh purchase, 10 % marketing costs, WACC 6 % (real), investment 250 €/kWh (LFP), 360 €/kWh (ZnBr), 275 €/kWh (NIB), lifetime 14, 25 and 10 years, respectively. Comparison of the three focus technologies.
10.5%
IRR LFP
NPV 2,802 kEUR · highest IRR
9.5%
IRR ZnBr
NPV 5,076 kEUR · highest NPV
110
LCOS LFP €/MWh
Minimum benchmark per cycle
104
LCOS ZnBr €/MWh
Lowest LCOS
Source: KPMG AG Wirtschaftsprüfungsgesellschaft, „Investment Case: Stationary Battery Storage“, February 2026 (Figures 5, 7, 9 and 10, p. 18–21). LFP: NPV 2,802 kEUR, IRR 10.5 %. ZnBr: NPV 5,076 kEUR, IRR 9.5 %. NIB (Sodium-ion battery): NPV 601 kEUR, IRR 7.2 %. Project-specific values (unlevered) in a simplified comparison calculation; actual projects may differ significantly.
CAPEX ranges 2026
| System Size | Configuration | CAPEX range | €/kWh |
|---|---|---|---|
| 1 MW | 2 MWh, 2-hour profile | ~500.000 € | ~250 €/kWh |
| 5 megawatts | 10 MWh, 2-hour profile | 1.75–2.0 million € | 175–200 €/kWh |
| 10 MW | 20 MWh, 2-hour profile | €3.5–4.0M | 175–200 €/kWh |
CUBE CONCEPTS benchmark values (project experience 2025/2026), turnkey, indicative. For comparison: the KPMG comparison calculation assumes €250/kWh for LFP (10 MW / 40 MWh).
Immediate investment program – tax levers 2025–2027
For BESS acquisitions between 1.7.2025 and 31.12.2027, the declining-balance depreciation under the Immediate Investment Program applies. It can be combined with the existing special depreciation under §7g EStG, whose scope of application is narrower:
1.
Declining-balance depreciation up to 30 % in the first year (§7, paragraph 2 of the EStG) – for all companies regardless of size. Specifically: up to three times the straight-line depreciation, with a maximum of 30% of the acquisition cost per year; in subsequent years, based on the remaining book value.
2.
Special AfA §7g, paragraph 5 of the EStG up to 40 % spread over up to 5 years – only for businesses with a previous year's profit of up to €200,000 (uniform profit limit since the JStG 2020, §7g, paragraph 6, item 1 of the EStG).
What does this mean for industrial companies? Medium-sized businesses and large industry typically do not use the degressive AfA (30 % in the first year) above the 200,000 € profit threshold. The combination with the 70 first- % year deduction only applies if the business meets the profit threshold. Tax advice is recommended for individual cases.
BESS qualifies as movable property of the investment assets. Source: Federal Law Gazette (BGBl.) 2025 I No. 161 of 18.07.2025; §7(2) EStG; §7g(5) in conjunction with §6 EStG. The information is for informational purposes only; no tax advice is provided. More about the Immediate Investment Program (article on PV systems) →
Location profiles
Which revenue mix is suitable for which location profile?
Multi-use is not a one-size-fits-all strategy. What makes economic sense depends on grid connection, load profile, PV system, and planning horizon.
Location with peak load problem
The demand charge is based on the highest quarter-hour in the billing year: A single peak determines the demand costs for the entire year. Every kilowatt saved at the load peak has immediate, measurable value. BTM comes first – FTM complements.
Location without peak load problems
Free grid connection capacity is the ticket to the balancing energy markets. Without peak load pressure, FTM is immediately the strongest lever. FTM comes first – BTM follows in Phase III.
Profile 1 – Energy-intensive production with peak loads
Primary: Peak Shaving (BTM)
§19 paragraph 2 sentence 1 StromNEV (until 2028) as a lever · FCR additionally from 1 MW system size · Connection mostly medium voltage
Profile 2 – Industry with substantial grid connection
Primary: aFRR + mFRR + Arbitrage (FTM)
240,000–320,000 €/MW/year FTM yield potential · BTM self-consumption in Phase III – free connection capacity is the ticket to entry
Profile 3 – PV site with MiSpeL suitability
Primary: Self-consumption + Peak Shaving (BTM)
Since MiSpeL (October 2026): BTM + FTM combined, hybrid operation without EEG loss according to § 19, paragraph 3b of the EEG
Profile 4 – KUEBLL sector eligible for the industrial electricity price
BESS as industrial electricity price reinvestment
Reinvestment obligation for the industrial electricity price: energy storage units eligible, implementation and financing by third parties permitted, therefore also possible under Contracting
Business models
Buy vs. Contracting – a decision about investment style and distribution of proceeds
Both models are eligible for credit as an investment in energy storage under the industrial electricity price; according to the BAFA, a third party may also finance the measure. What differs is the contractual structure – not the technology.
| Aspect | BESS Contracting (CPFS) | BESS purchase |
|---|---|---|
| Customer CapEx | €0 | full investment (CAPEX-Backbone) |
| Customer revenues | 25% of net market revenues from day 1 | 100% of all revenues and savings |
| CUBE revenues | 75% of net market revenues | 0% |
| Balance Sheet | Off-balance-sheet treatment possible (subject to IFRS 16 assessment) | On-Balance |
| Contract Structure | Service and Profit Share Agreement | Sales contract + Maintenance contract |
| Industrial electricity price reinvestment | ✓ eligible: implementation by third parties (BAFA guidance note, Chapter 3.5) | ✓ eligible: own purchase |
| Hardware ownership | CUBE | Customer |
Both models are built on the same foundation: manufacturer-independent hardware choice, identical CUBE open-book calculation, identical control phase logic. What differs is the contractual structure – not the technology. Both models count as reinvestment in energy storage under the industrial electricity price.
How Multi-Use Arrives in the Business Model
Multi-Use doesn’t start with the storage unit – but with the unused grid connection reserve.
Every industrial site pays for reserved connection capacity – demand charge, basic fee, grid fee. Based on CUBE CONCEPTS’ experience, most sites use only 30–50 % of it. CPFS turns this silent reserve into a revenue stream – without own investment, without hardware risk, with a 25 % profit share for the customer from day 1.
Reserved connection
capacity
today only 30–50% used
Multi-Use BESS
FTM + BTM on one asset
Revenue stack
240–320 k€/MW/year Gross
Most providers ask “How much can you invest?” or “What is the size of your roof area?”. We ask: How much of your reserved, already paid-for grid connection capacity is unused today? Multi-use storage utilizes exactly this silent reserve without requiring new connection capacity to be applied for. This is a real advantage: In 2025, only 8 % of the connection requests for battery storage were granted in the distribution grid (BNetzA/SMARD).
What sets us apart
Three points that differentiate CUBE CONCEPTS from hardware manufacturers and utility-scale providers
The German BESS market is roughly divided into two camps: hardware manufacturers selling their own technology, and utility-scale providers supplying investment funds. CUBE CONCEPTS is neither.
01
Manufacturer-independent
We run a tender for every project – at least 3 comparative offers. No proprietary system, no manufacturer lock-in. The hardware selection follows the load profile, not the catalog stock.
Hardware manufacturers sell their own technology – that’s their business model.
02
Open Book before contract signing
Full cost transparency before signing: CAPEX, OPEX, profit-share logic, marketing costs. No fixed price without a breakdown. You see what you're buying.
Fixed-price offers without a breakdown are common in the market.
03
0 € CapEx + 25 % Profit Share
CPFS Contracting for C&I customers: no own investment, no hardware risk, 25 % of the net market revenue from day 1 to the customer – CUBE 75 %. Under the industrial electricity price, the storage system counts as a reinvestment, even if CUBE finances it.
Utility-scale providers typically sell to investment funds – not to industrial companies.
Based on 150+ energy projects implemented across Europe (PV so far). Industrial electricity price: Directive of 27.04.2026 · BAFA leaflet on decarbonization measures, Chapter 3.5 · CISAF No. 121–122.
Regulatory Levers 2026/2027
Six levers changing multi-use profitability in 2026/2027
Multi-Use is not a natural law, but the result of current regulatory policies. These six levers are the most important – and they do not act in isolation, but as a coordinated shift.
§118 para. 6 EnWG
Exemption for electricity fed back into the grid
20 years of exemption from grid fees on electricity drawn from the grid, insofar as it is fed back; since December 2025 also for partial feed-back. Commissioning by August 4, 2029; according to the AgNes draft, investment decision before January 1, 2027.
Section 19 (2) sentence 1 StromNEV / AgNes
Atypical grid usage privilege → AgNes 2029
Until 31.12.2028: Discount of up to 80 % if the peak load in the peak load time windows is significantly below the annual peak load. From 01.01.2029 according to the AgNes draft: no successor to atypical grid usage, capacity price on the ordered capacity, consumption above it at 2 to 3.5 times the energy charge. Discounts only in return for system-supportive flexibility, e.g. with storage.
MiSpeL since October 2026
Hybrid storage without EEG loss
Market integration of storage systems and charging points: Simultaneous EEG operation and FTM marketing without loss of EEG subsidies under § 19, paragraph 3b of the EEG. PV sites can now combine arbitrage and EEG feed-in for the first time.
EEG Amendment 2027 (government draft)
Direct marketing for new installations
According to BT-Drs. 21/7867: Direct marketing obligation for new installations (phased), permanent feed-in limit of 50 % for building-mounted PV below 100 kW, two-sided contracts for difference from 100 kW. Not yet adopted, planned from 1.1.2027. With storage, more PV electricity can be self-consumed instead of being fed in under the cap.
Industrial electricity price (approved 16.04.2026)
Reinvestment obligation
At least 50 % of the granted amount must be invested within 48 months in measures to reduce the costs of the electricity system; energy storage explicitly mentioned. Eligible: KUEBLL sub-list 1, according to the BMWE, 91 sectors and sub-sectors. A third party may implement and finance the measure; BESS Contracting is thus possible without customer CapEx.
EnWG and BauGB amendments Dec. 2025
§11c EnWG + §35 BauGB
§11c EnWG since 23.12.2025: Energy storage systems are in the overriding public interest and take priority when weighing protected interests. §35, Para. 1 No. 11 BauGB: Battery storage systems spatially and functionally linked to an existing renewable energy installation are privileged in outlying areas, No. 12 covers larger storage systems near substations.
Source: §118, paragraph 6, EnWG · §19, paragraph 2, StromNEV · BNetzA, AgNes-Draft of the regulation from 06.08.2026 · BNetzA, MiSpeL-regulation · BT-Drs. 21/7867 · Industrial electricity price directive from 27.04.2026 · §11c EnWG · §35 BauGB
Who markets on the market
Multi-use FTM marketing runs through prequalified balancing reserve providers
Only providers that are prequalified with the transmission system operators (Balancing Service Providers, BSP) may supply balancing energy. Industrial storage systems are therefore usually marketed through such a provider, which also trades on the spot market.
Vertically integrated aggregator
Multi-market in parallel
Balancing energy + EPEX Spot
According to the transmission grid operators’ provider list (as of July 8, 2026), 44 companies in Germany are prequalified for balancing reserve. Top-tier aggregators operate their own trading algorithms, are prequalified themselves (rather than going through intermediaries), and market simultaneously in the day-ahead, intraday continuous, and balancing energy markets. This vertical integration determines the revenue difference: Those who have their own software, operate their own data stack, and are directly connected to the transmission grid operators achieve outperformance compared to average market participants.
The CUBE CONCEPTS standard requires a vertically integrated aggregator with BSP prequalification, proprietary trading algorithms, and verifiable multi-market optimization. A pure hardware sales structure without prequalification or proprietary trading software does not achieve this level of depth.
Source reference: Transmission system operators, regelleistung.net: Balancing reserve provider list (as of 08.07.2026) and PQ conditions according to EU guideline SO GL
Safety & Fire Protection
What "multi-use" means in terms of safety
Multi-use increases the cycle frequency, but not the safety requirements – these are technologically independent of the operating mode in stationary LFP storage systems.
Thermal Stability
LFP (Lithium Iron Phosphate) cells are cobalt-free and more thermally stable than other lithium-ion chemistries. Standard for stationary industrial storage.
VdS-certified fire protection concepts
Standardized fire suppression systems, surge protection, and temperature control in enclosed container solutions with a defined IP rating.
Standard-compliant grid integration
VDE-AR-N 4110/4120 (medium/high voltage), IEC 62933-5-2 (safety of battery storage systems), redundant BMS architecture, lightning protection IEC 62305.
The multi-use control system does not affect safety hardware – BMS, fire alarm and extinguishing systems are independent of the operating mode. An FCR system and a multi-use system have the same safety requirements.
Definition clarification
Multi-Use is not Multi-Market – why the distinction is economically crucial
In the German BESS market, these terms are often used interchangeably. In fact, they describe different revenue models with different economic implications.
Multi-market
FTM Marketing Stack (Front-of-the-Meter)
- Day-Ahead Trading – Offers for the following day
- Intraday Continuous – short-term price fluctuations, 5-minute lead time
- FCR (frequency containment reserve) – ~0.3 full cycles/day
- aFRR + mFRR – Secondary/Minute Reserve
- Negative spot prices – Charging arbitrage in surplus hours
Pure FTM optimization – the storage system sits on the public grid, in front of the plant meter.
Multi-Use
FTM + BTM on the same asset
- All Multi-Market Revenue Streams – FCR, aFRR, mFRR, Spot, Intraday
- Peak Shaving (BTM) – against the demand charge
- §19 atypical grid usage / AgNes optimisation – Grid fee reduction
- Self-consumption optimization – with or without a photovoltaic system
- UPS / Island operation capability – Security of supply
- Co-Location with MiSpeL – PV + BESS without EEG loss
Multi-Market PLUS BTM applications on the same system – that is the economic core of Multi-Use.
Multi-Market is therefore a subset of Multi-Use. Anyone operating a pure Multi-Market storage solution leaves the BTM lever unused – peak shaving, §19/AgNes optimization, and self-consumption are not included there. The difference between Multi-Market and Multi-Use is exactly the BTM stack: significant for industrial sites with peak loads, regulatory grid fee leverage, or PV capacity.
Industrial electricity price 2026
Industrial electricity price: How companies meet the reinvestment obligation with a battery storage system
The EU Commission approved the industrial electricity price on 16 April 2026 (SA.120495). The relief is linked to a reinvestment obligation under the EU aid framework CISAF: At least 50 % of the granted amount must be invested in measures that reduce the costs of the electricity system, energy storage explicitly included.
Eligibility – KUEBLL sub-list 1
Offtake points in Germany in economic sectors with a significant risk of relocation (sub-list 1 of Annex I to the KUEBLL) are eligible; according to the BMWE, these are 91 sectors and sub-sectors with potentially around 9,500 companies, for example from steel, chemicals, aluminum, paper and glass. Other sectors may be added following a decision by the European Commission.
Calculation – 50 % on 50 %
Half of the eligible consumption of an offtake point is subsidized. The difference price is generally 50 % of the reference price (average of the EEX base-load annual futures of the previous year); the remaining price must not fall below the target price of 5 ct/kWh. For 2026: Reference price 8.744 ct/kWh, difference price 3.744 ct/kWh, around 4.1 ct/kWh including the bonus. Billing years 2026 to 2028; application for 2026 retroactively in 2027 to BAFA (deadline March 31, 2027), payment in the following year.
Reinvestment obligation – at least 50 %
At least 50 % of the granted amount must be invested within 48 months (technically justified up to 72): in renewable generation (including new PPAs), energy efficiency, demand-side flexibility (including energy storage, electrification, electrolysers, load management), or grid infrastructure. The measures must be located in Germany and may not receive any other aid. The directive explicitly mentions „investments in energy storage“.
Flexibility bonus – +10 %
Those who commit to investing at least 80% of % their investment commitment in demand-side flexibility when applying for a subsidy receive a bonus of 10%% of the basic benefit amount. In addition, 75% of % this bonus must be invested in decarbonization measures. A battery storage system counts as flexibility: The BAFA gives the example of a power storage system that reduces peak loads, optimises PV self-consumption, or takes advantage of price differences in the spot market.
How Contracting fulfils the obligation
In BESS Contracting, CUBE CONCEPTS bears the full investment. This is permissible: According to the directive and the BAFA guidance note, a third party may implement the measure “not only in material terms but also in financial terms”. The measure does not have to be located at the offtake point applied for, but it must be in Germany. The applicant remains responsible for the implementation and submits the third party’s evidence and declarations of consent. Upon request, the BAFA confirms in advance that a measure is eligible.
Source: Industrial electricity price guideline of 27.04.2026, BAnz AT 06.05.2026 B1, No. 3.1, 4.1, 4.4, 5.1, 5.3 · BAFA brochure on decarbonization measures, as of 04.08.2026, Chapter 3.4–3.5 · BAFA, Industrial electricity price · BMWE, press release 16.04.2026 · EU Commission, CISAF item 121–123 · KUEBLL Appendix I, Part List 1
References
150+ energy projects completed across Europe. Tušimice battery storage with 50 MW / 100 MWh currently under construction.
Selected industrial companies for which CUBE CONCEPTS has completed energy projects, so far in photovoltaics. Currently under construction: Tušimice battery storage, 50 MW / 100 MWh, first expansion stage.
TI Automotive
Magna
Valeo
Voestalpine
Tenneco
ITW
In preparation (2026)
Industrial location Saxony – 1 MW / 2 MWh BESS, 1,895 kWp PV capacity, multi-use modeling in three regulatory configurations
Pipeline Project
Thermal Management Solutions DE Oberboihingen GmbH (WAHLER) – BESS Contracting in preparation
PV system in operation since summer 2025. Industrial storage in the Contracting model as the third step of the sustainability strategy. Manufacturer of high-quality thermostat and temperature control technology. Managing Director Holger Kiebel: “Battery storage is the logical next step.”
FAQ
Multi-Use BESS – Answers for Decision Makers
The twelve most frequently asked questions about multi-use, control logic, economic viability, and regulatory aspects.
What does a battery storage system cost per cycle – and when is multi-use worth it?
The costs per cycle result from investment, degradation, and operation per discharged MWh; the LCOS serves as a benchmark, for LFP €110/MWh in the KPMG comparison calculation (February 2026), with a 2.1 % capacity loss per year. An arbitrage cycle is only worthwhile if the spread exceeds these proportional costs; the CUBE EfficiencyUnit only executes it when the margin is positive. FCR is predominantly paid for availability and only causes around 0.3 cycles per day.
How much FTM revenue can a 1 MW battery storage system generate in a year?
CUBE CONCEPTS expects a gross revenue potential of €240,000–320,000 per MW per year from FCR, aFRR, mFRR and arbitrage, before around €55,000 in OPEX. According to the ISEA Battery Revenue Index, the cross-market potential of a 2-hour storage system in 2025 was around €259,000/MW, 16% below 2024. A PV installation is not required for this.
By when must a battery storage system be commissioned to receive the grid fee exemption pursuant to Section 118 of the Energy Industry Act (EnWG)?
Section 118, paragraph 6 of the EnWG exempts storage systems that go into operation by August 4, 2029 from grid fees on electricity drawn from the grid for 20 years, insofar as the electricity is fed back into the grid. According to the AgNes draft determination of the Federal Network Agency of 06.08.2026, this only applies to new projects if the final investment decision is made before the determination is announced, planned for January 1, 2027. With an existing grid connection, CUBE CONCEPTS expects 6–12 months until commissioning.
Can a battery storage system simultaneously utilize the §19 grid charge privilege and FCR reserve energy?
Yes – provided the control system is compliant with §19. The CUBE EfficiencyUnit maintains FCR SoC (~50 %) and automatically blocks charging operations during peak load time windows. Both revenue streams operate simultaneously without manual intervention.
What has MiSpeL changed for companies with PV systems since October 2026?
Since the MiSpeL determination of October 1, 2026, EEG operation and FTM marketing can be combined through the same storage system without losing the EEG subsidy. PV sites can now combine arbitrage and EEG feed-in for the first time, without the previous either-or situation. Until September 30, 2027, the consent of the grid operator and the metering point operator is required for this.
How is §19 compliance documented for the annual reporting to the network operator?
The CUBE EfficiencyUnit records every charging process and every period relevant to the peak load time windows with timestamps. The annual proof (deadline: June 30 of the following year) can be exported directly and is archived in an audit-proof manner – no manual proof required.
What is the difference between a multi-use-capable and a multi-use-optimized battery storage system?
Multi-Use-capable means: Hardware technically supports multiple modes. Multi-Use-optimized means: The control logic automatically prioritizes revenue channels, dynamically calculates cycle thresholds, and documents §19 compliance without manual intervention. The control logic, not the hardware, is crucial.
Can a battery storage system be operated economically without its own PV system?
Yes. FTM multi-use (FCR, aFRR, mFRR, arbitrage) is completely independent of PV. The FTM revenue potential of €240,000–320,000 per MW/year comes exclusively from market arbitrage and balancing energy – without any self-generation.
How is the CUBE EfficiencyUnit prepared for the AgNes system starting in 2029?
What is the LCOS in battery storage systems – and how does it affect the multi-use economy?
LCOS (Levelized Cost of Storage) is the discounted total cost per discharged MWh over the lifetime: for LFP 110 €/MWh, for ZnBr 104 €/MWh (KPMG AG, Feb. 2026). For multi-use, LCOS is the minimum benchmark per cycle: an arbitrage cycle is only worthwhile if the spread is above it. FCR, on the other hand, is mostly remunerated for availability.
What tax incentives are available for BESS investments in 2026/2027?
The Investment Acceleration Program (BGBl. 2025 I No. 161 of 18.07.2025) allows for a degressive % AfA for purchases from 1.7.2025 to 31.12.2027, up to 30 in the first year (§7, paragraph 2, EStG). The existing special AfA under §7g, paragraph 5, EStG (up to 40 % distributed over up to 5 years) is combinable; it is limited to businesses with pre-year profits up to €200,000. First, when combined, they often result in the often cited 70 %-year-old first-year deduction – for medium-sized and large industrial companies above the profit threshold, only the 30 %-year-old AfA applies. BESS qualifies as a movable asset of the investment assets. Tax-specific case review recommended. More information: Investment immediate program (contribution to PV systems) →
What regulatory reliefs apply to industrial storage since the end of 2025?
Two levers have applied since December 23, 2025: (1) According to §11c EnWG, the construction and operation of energy storage systems are in the overriding public interest and take priority when weighing protected interests; for electricity storage systems this has applied since 2023. (2) §35, Paragraph 1, No. 11 and 12 of the Building Code (BauGB) privilege battery storage systems in outlying areas: when spatially and functionally linked to an existing renewable energy installation (No. 11), or from 4 MW at most 200 m from a substation or a power plant of 50 MW or more (No. 12). Note: Energy Sharing under §42c EnWG (since June 1, 2026) is only open to companies that are SMEs, not to large industry.
Next step
Analyzing the multi-use potential – site-specific
Section 118(6) of the EnWG – Time until the due date for the investment decision (AgNes draft)
59 days
January 1st, 2027
Investment decision (draft)
August 4, 2029
Commissioning §118
20–27 T€/month
unused gross revenue potential at 1 MW
Submit your load profile. CUBE CONCEPTS calculates BTM and FTM potentials separately – based on current market data and the AgNes draft determination of 06.08.2026. Open-book modeling in three regulatory configurations, free of charge, no commitment required.
Without a timely investment decision, the new fee system (AgNes draft) applies to new storage systems from 2029 · calculated gross market revenue of €20,000–27,000 per month and MW
Note on content and status
As of: 09.10.2026. AgNes information based on the draft determination of 06.08.2026; the final determination is planned for the end of 2026. All regulatory information (CISAF, KUEBLL, AgNes, MiSpeL, §118 EnWG, EEG amendment 2027, Immediate Investment Program) is based on sources published at the time of writing; determinations, statutory ordinances and EU notifications may change. Tax statements are not tax advice – individual review by a tax advisor is required. Profitability figures (FTM revenues, IRR, NPV, payback) are market benchmarks or KPMG comparison calculations and not guaranteed returns. Site-specific modeling is required.
Further content
